0 Planning for Long-Term Care: How to Prepare for Future Needs and Expenses
- Assisted Living
- Author Arthur Lloyd
- 11-11-2026
Planning for Long-Term Care: How to Prepare for Future Needs and Expenses
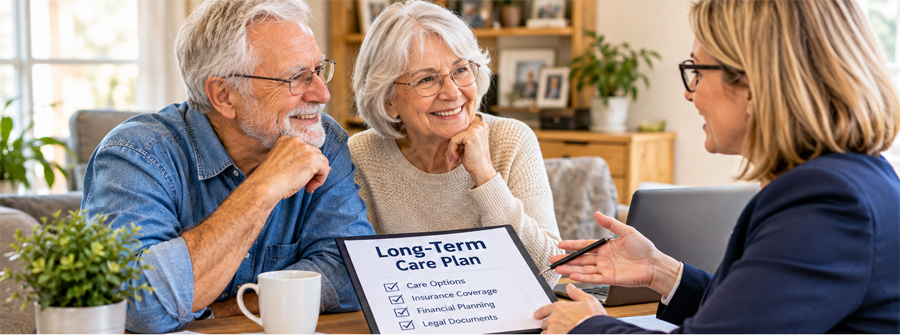
Long-term care planning is one of the most important steps older adults can take to protect their financial security and preserve their independence as they age. Although most people hope to remain healthy and self-sufficient throughout retirement, everyday activities such as bathing, dressing, preparing meals, and getting around safely can eventually become more challenging.
When additional assistance becomes necessary, the financial and emotional demands can be considerable. Without preparation, families may find themselves making difficult decisions under pressure, often while trying to balance care needs with limited financial resources.
Whether you hope to age in place at home or eventually move into an assisted living or nursing care community, planning can make a significant difference. Understanding your options, estimating potential expenses, reviewing insurance coverage, and organizing important documents can help you prepare for the future with greater confidence.
Here are several important considerations to help you develop a practical long-term care plan.
1. Understand Your Potential Long-Term Care Needs
Long-term care planning involves much more than setting aside money for future medical expenses. It means considering the type of assistance you might need, where you would prefer to receive it, and how those services could affect your retirement finances.
Not everyone requires the same level of care. Some older adults may need occasional help with household responsibilities, while others may eventually require daily personal assistance or around-the-clock supervision.
Your potential needs may depend on several factors, including:
- Health and mobility: Changes in physical health can make everyday activities more difficult.
- Living arrangements: Your home's layout, accessibility, and location may influence whether aging in place is practical.
- Family support: Relatives may be available to provide occasional assistance, but their ability to offer ongoing care should not be assumed.
- Personal preferences: Some people strongly prefer remaining at home, while others appreciate the convenience and social opportunities of a residential community.
Thinking about these circumstances before assistance becomes necessary gives you more time to explore arrangements that fit your preferences and financial situation.
2. Explore the Different Types of Short- and Long-Term Care
One common misconception about long-term care is that it
Content Marketing Offers the Highest Return On Investment
Online content marketing and advertising is currently the second-highest method of promoting businesses, following only Television, which, for now, remains in the number one position. Experts predict digital ads will surpass TV and never look back. For cost-effectiveness and the ability to target your audience, nothing matches the ROI of digital marketing. Learn More
Digital Marketing Offers Three Opportunities To Reach Your Audience
Studies show that most people use their phones to search for content that addresses their current needs, then switch to their computers for more in-depth research before making a final decision or purchase. With three different platforms- computers, tablets, and phones- it is essential to ensure your audience can follow your content and ads on any device. The upside to this is that you have three opportunities to reach them. All of our Websites are developed to work flawlessly on all three platforms. Learn More
automatically means moving into a nursing home. In reality, several care arrangements are available, and the appropriate choice depends on an individual's health, independence, and support requirements.
Understanding the differences can help you identify which services might eventually be appropriate.
In-home care
In-home care allows older adults to remain in familiar surroundings while receiving assistance with activities such as bathing, dressing, meal preparation, housekeeping, and transportation. Depending on individual needs, services may range from occasional visits to more extensive daily assistance.
Learn more about services that help older adults remain at home.
Adult day services
Adult day programs provide supervised activities, social interaction, and varying levels of personal assistance during daytime hours. These services can help older adults maintain social connections while giving family caregivers time to manage work and personal responsibilities.
Senior or Independent living
Independent Living / Senior Living are houses, apartments, condominiums, or communities, designed for active (typically 55+) older adults who are still self-sufficient and prefer a maintenance-free lifestyle. These typically include social activities and shared amenities for people without the need for daily care assistance.
Assisted living
Assisted living communities offer residential accommodations, meals, personal assistance, and opportunities for social engagement. Residents generally maintain some independence while receiving help with activities they find difficult to manage alone.
Explore assisted living services and considerations.
Nursing home care
Nursing homes provide more comprehensive care for individuals who require ongoing supervision, skilled nursing services, or assistance with more complex health needs.
Memory Care
A specialized, secure environment within communities tailored for seniors living with Alzheimer's disease or other forms of dementia. These are reserved for people without family members who can care for them or those who are beyond their family’s ability to care for them and require professional help.
Continuing Care Retirement Communities (CCRCs)
Continuing Care Retirement Communities, also known as Life Plan Communities, offer multiple tiers of care (from independent living to nursing care) on a single campus so residents can transition to the different types of care as their needs change.
Costs and services vary considerably depending on the location, facility, and level of care required.
When comparing providers, look beyond advertised monthly prices. Ask whether medication management, transportation, additional personal assistance, and other services involve separate charges.
3. Understand What Medicare and Medicaid Actually Cover
One of the biggest surprises for retirees is discovering that Medicare does not generally cover extended custodial long-term care.
Medicare may pay for certain medically necessary skilled nursing or rehabilitation services when specific eligibility requirements are satisfied. However, it generally does not cover ongoing assistance with everyday activities such as bathing, dressing, eating, or using the bathroom when custodial care is the primary need.
This distinction is important because many older adults assume their existing health insurance will cover most future care expenses.
Medicaid is another potential source of assistance. Unlike Medicare, Medicaid can cover qualifying long-term services and supports for eligible individuals, including certain nursing home and home-based care services.
However, eligibility depends on financial and other requirements that vary by state. Some programs also have specific application procedures and limitations.
Visit Medicaid's Long-Term Services and Supports resource to learn more.
Private long-term care insurance provides another potential funding option. Depending on the policy, coverage may include qualifying home care, assisted living, nursing home services, and other forms of assistance.
Policies differ in their benefit amounts, waiting periods, covered services, exclusions, and maximum payment periods.
Reviewing these distinctions before purchasing coverage or relying on an existing policy can help prevent unpleasant financial surprises later.
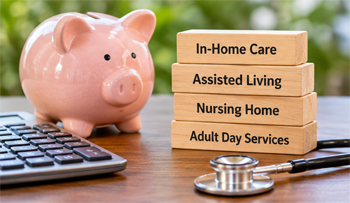
4. Estimate Long-Term Care Costs Before You Need Them
Developing a realistic long-term care budget is essential for protecting retirement savings. Unfortunately, many people underestimate how quickly expenses can accumulate when regular assistance becomes necessary.
Rather than relying exclusively on national averages, begin by researching actual care costs in the area where you expect to live.
Contact several home care agencies, assisted living communities, and nursing facilities to request estimates. Ask about initial fees, monthly charges, additional services, and potential increases over time.
Your long-term care budget should account for several categories:
- Regular care expenses: Caregiver visits, residential fees, personal assistance, and medical supplies.
- Household obligations: Mortgage or rent payments, utilities, groceries, insurance, and property taxes.
- Home modifications: Potential expenses for improved accessibility, bathroom adjustments, ramps, and other safety improvements.
- Unexpected expenses: Emergency transportation, additional caregiving hours, or changes in health that require more extensive assistance.
- Inflation: Future care services may cost considerably more than today's estimates.
- Family responsibilities: A spouse or other dependent may continue to rely on your retirement income and savings.
Once you have estimated potential expenses, compare them with retirement income, savings, insurance benefits, and other available resources.
The objective is not necessarily to predict every future expense. Instead, it is to understand your financial position and identify potential gaps before they become difficult to manage.
5. Review Your Existing Financial Resources and Insurance
Paying for long-term care does not necessarily require relying on one source of funding. A combination of retirement income, savings, insurance benefits, and other financial resources may provide greater flexibility.
Begin by reviewing your current financial arrangements.
Consider the following:
- Retirement accounts and investment income.
- Social Security and pension benefits.
- Existing life insurance policies.
- Long-term care insurance, if applicable.
- Savings and emergency reserves.
- Other assets that could potentially help fund future expenses.
If you already have long-term care insurance, examine the policy carefully. Understand the benefit limits, qualifying conditions, waiting periods, and services covered.
It is also worth reviewing life insurance policies that may no longer serve the same purpose they did when originally purchased.
6. Could an Existing Life Insurance Policy Help Pay for Long-Term Care?
Life insurance is often purchased years before retirement to provide financial protection for spouses, children, or other dependents. However, circumstances and financial priorities can change as people grow older.
A policy that once served an important family protection purpose may deserve another look when retirement and long-term care expenses become more immediate concerns.
Depending on the policy and individual circumstances, several possibilities may be worth exploring.
Retaining the policy: Keeping existing coverage may still make sense if the death benefit remains important to your family or beneficiaries.
Using available policy benefits: Certain policies include accelerated death benefits that may provide access to part of the death benefit if specific qualifying conditions are met. Some permanent life insurance policies also accumulate cash value that may be accessible through withdrawals or loans, subject to policy provisions and potential financial consequences.
Exploring a life settlement: Another possibility for certain policyholders is a life settlement.
A life settlement involves selling an eligible life insurance policy to a third-party buyer in exchange for a lump-sum payment. The amount offered depends on factors such as the policy's death benefit, premiums, the insured person's age and health, and other considerations.
The proceeds could potentially help pay for long-term care, assisted living, or other retirement expenses.
For individuals interested in learning more, Windsor Life Settlements offers a life settlement calculator that can help policyholders explore the potential value of an eligible policy.
An online estimate is not a guaranteed purchase offer, and not every policy qualifies.
Before pursuing a life settlement, consider the potential tax consequences, the loss of the policy's death benefit, and how the transaction could affect eligibility for certain public benefits. Comparing alternatives and seeking independent financial, legal, or tax advice can help determine whether this option is appropriate.
7. Create a Personal Long-Term Care Planning Checklist
Once you understand the available care arrangements and potential financial resources, the next step is putting your plans into action.
An organized checklist can make the process more manageable.
Identify your preferences. Think about where you would ideally receive assistance. Would you prefer to remain at home, move closer to family, or consider an assisted living community?
Evaluate your living environment. Consider stairs, bathroom accessibility, transportation, neighborhood safety, and the availability of nearby support.
Research local care providers. Compare services, availability, pricing, licensing, and additional fees. Visit communities when possible and ask questions about their care arrangements.
Review your financial resources. Examine retirement income, savings, insurance policies, and other assets that might help cover future expenses.
Organize important legal documents. Discuss healthcare directives, financial powers of attorney, and other estate-planning documents with qualified professionals. These arrangements can help ensure that trusted individuals understand your wishes and have appropriate authority when necessary.
For additional guidance, see Five Important Legal Documents Seniors Should Have.
Communicate with family members. Share your preferences with trusted relatives or representatives. Make sure they know where important financial, medical, and legal documents are stored.
Finally, review your plan at least once a year or whenever significant changes occur in your health, finances, or family circumstances.
8. Find Local Resources That Can Help
You do not have to navigate long-term care planning entirely on your own. Numerous government agencies and nonprofit organizations provide information and assistance to older adults and their families.
One particularly useful resource is the federally supported Eldercare Locator.
This service connects older adults and caregivers with local organizations offering services such as:
- Community-based aging assistance.
- Transportation and meal programs.
- Caregiver support services.
- Home-based assistance.
- Information about local long-term care resources.
You can also call 1-800-677-1116 to speak with someone who can help identify services in your community.
Exploring these resources early can help you understand what assistance may be available before making major financial or residential decisions.
Frequently Asked Questions About Long-Term Care Planning
When should I start planning for long-term care?
Ideally, begin planning while you are healthy and financially able to evaluate your options. Starting early provides more time to review insurance, organize savings, research care providers, and communicate your preferences with family members.
Does Medicare pay for assisted living or nursing home care?
Medicare generally does not cover assisted living or ongoing custodial nursing home care. It may cover certain qualifying skilled nursing and rehabilitation services for limited periods under specific conditions. Medicaid may cover qualifying long-term care services for eligible individuals.
Can family members provide all my future care?
Family members may be able to provide some assistance, but relying entirely on relatives can create significant physical, emotional, and financial demands. Discuss realistic responsibilities and alternative arrangements before making family caregiving your primary plan.
What if I do not have enough retirement savings to cover long-term care?
Explore Medicaid eligibility, community-based assistance programs, veterans' benefits when applicable, and local nonprofit resources. You may also want to review existing insurance policies and other financial options. Eligibility requirements vary, so consult qualified professionals before making major decisions.
Planning Today Can Protect Your Options Tomorrow
Although nobody knows exactly what their long-term care needs will be, preparing for the possibilities can make retirement more secure and future decisions less overwhelming.
Understanding available care arrangements, researching local expenses, reviewing insurance coverage, and organizing important legal documents all contribute to a more effective plan.
Most importantly, remember that long-term care planning is about more than paying future bills. It is about maintaining as much independence as possible, protecting the financial resources you have worked hard to accumulate, and ensuring your personal preferences remain part of important decisions.
Even modest steps taken today can provide greater flexibility, reduce uncertainty, and help you approach the future with greater confidence and peace of mind.
You can read more articles on this topic here.
Disclaimer: This article is for general educational purposes only and is not legal, tax, or financial advice. Senior Living, Assisted Living, and Home Care rules and regulations vary by state. Consult appropriately qualified professionals about your individual needs.
All Images generated by AI
A special thank you to Arthur Lloyd for contributing this article.
Discover the secrets to aging gracefully and living your best life with Enjoying Aging – your ultimate resource for health, wellness, and financial wisdom!
If you enjoyed this article or have a topic you would like to suggest for a new article, please leave a comment in the form below.