0 Smart Estate Planning Mistakes to Avoid After Age 50
- Estate planning
- Author Sara W.
- 10-17-2026
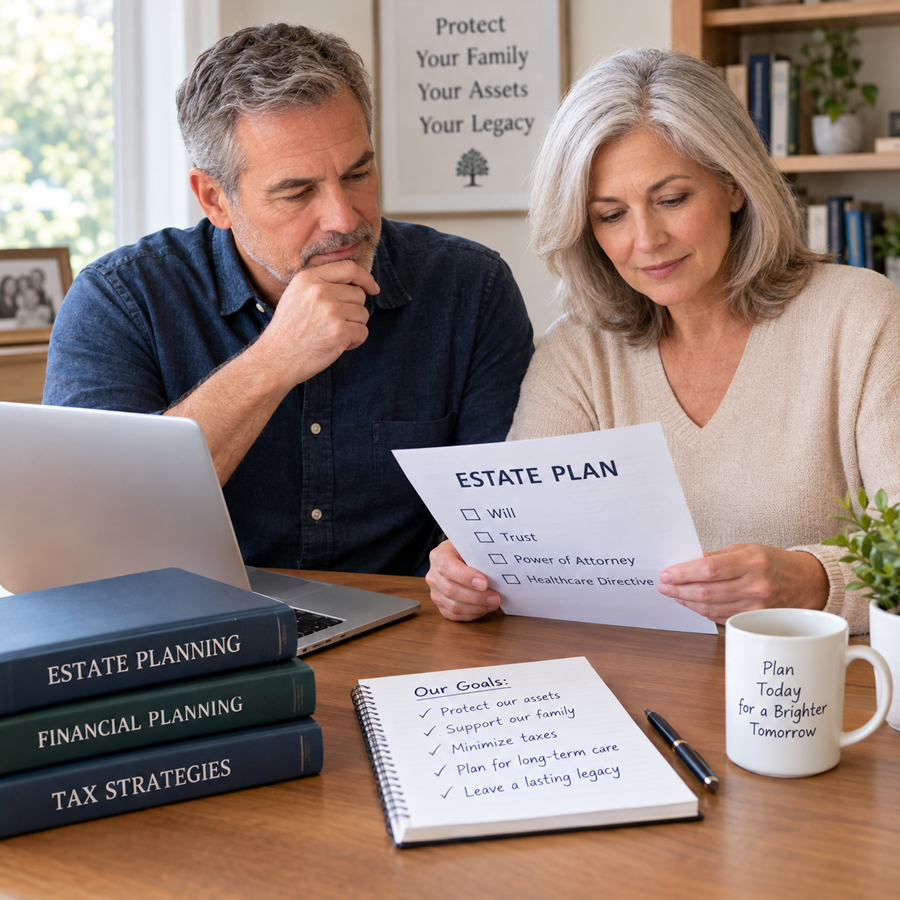
Smart Estate Planning Mistakes to Avoid After Age 50
Reaching your 50s is an excellent time to take a closer look at your financial future, protect the assets you've worked hard to build, and consider the legacy you want to leave behind. As retirement approaches, family circumstances change, and long-term financial goals evolve, estate planning after age 50 becomes an increasingly important part of protecting your wishes and your loved ones.
Unfortunately, many people make avoidable estate planning mistakes that can lead to family disputes, unnecessary expenses, legal complications, and delays in transferring assets to their intended beneficiaries.
Estate planning isn't something you do once and forget. It's an ongoing process that should evolve as your finances, relationships, and priorities change.
The good news? By understanding common estate planning mistakes and taking steps to avoid them, you can help protect your assets, make your wishes clear, and give your family greater peace of mind.
Why Estate Planning After Age 50 Requires a Fresh Look
Your financial priorities in your 50s and beyond may look very different from those you had in your 30s or 40s. You may have accumulated retirement savings, purchased real estate, started a business, remarried, or become a grandparent.
You may also be thinking more seriously about healthcare costs, long-term care, and who will manage your financial affairs if you become unable to do so yourself.
These changes make it important to review your estate plan regularly rather than relying on a will or other documents prepared years ago.
An effective estate plan should address several key questions:
- Who should inherit your assets?
- Are your retirement accounts and insurance policies set up to benefit the right people?
- Who will manage your finances if you become incapacitated?
- Who can make healthcare decisions on your behalf if you cannot communicate your wishes?
- How can you help minimize unnecessary legal expenses, delays, and potential tax liabilities?
Failing to address these questions can leave important decisions to the courts or state law, depending on your circumstances. A thoughtful, regularly updated estate plan helps ensure that your wishes remain clear and your family understands how to carry them out.
1. Failing to Update Beneficiary Designations
One of the most common estate planning mistakes is neglecting to update beneficiary designations on retirement accounts, life insurance policies, and certain bank or investment accounts.
Content Marketing Offers the Highest Return On Investment
Online content marketing and advertising is currently the second-highest method of promoting businesses, following only Television, which, for now, remains in the number one position. Experts predict digital ads will surpass TV and never look back. For cost-effectiveness and the ability to target your audience, nothing matches the ROI of digital marketing. Learn More
Digital Marketing Offers Three Opportunities To Reach Your Audience
Studies show that most people use their phones to search for content that addresses their current needs, then switch to their computers for more in-depth research before making a final decision or purchase. With three different platforms- computers, tablets, and phones- it is essential to ensure your audience can follow your content and ads on any device. The upside to this is that you have three opportunities to reach them. All of our Websites are developed to work flawlessly on all three platforms. Learn More
When you first open an account, you may name a spouse, partner, child, or another trusted individual as the beneficiary. Years later, however, your circumstances may have changed significantly.
Divorce, remarriage, the birth of grandchildren, or the death of a beneficiary can all affect who you want to receive your assets.
Why Outdated Beneficiary Records Can Cause Problems
Beneficiary designations often determine who receives assets from accounts that pass directly to named beneficiaries. In many cases, those designations take precedence over conflicting instructions in a will, subject to applicable law and account rules.
For example, suppose you named your former spouse as the beneficiary of a retirement account years ago. If you later divorce and update your will but forget to change the account's beneficiary designation, the former designation could still affect who receives those funds.
The outcome depends on the account, applicable law, and any relevant agreements or legal orders. This is why reviewing beneficiary information is so important.
Best Practices for Reviewing Your Accounts
Make beneficiary reviews part of your regular financial routine.
- Review retirement accounts, life insurance policies, and other accounts with beneficiary designations at least annually.
- Confirm that both primary and contingent beneficiaries are correctly identified.
- Revisit your choices after major life events, including marriage, divorce, births, deaths, or significant changes in family relationships.
- Check that your designations align with your current estate plan.
- Seek professional guidance when naming a trust, a minor, or someone whose eligibility for needs-based benefits could be affected by an inheritance.
A financial planner can help you organize your accounts and understand how your choices fit into your broader retirement strategy. An estate planning attorney can help resolve legal questions involving beneficiary designations and your will.
The goal is simple: make sure your assets are positioned to reach the people you intend to benefit.
2. Overlooking Incapacity and Long-Term Care Planning
Estate planning isn't only about what happens after death. It should also address what happens if you become seriously ill, experience an accident, or develop a condition that prevents you from managing your financial affairs or making healthcare decisions.
Without appropriate legal documents, your family may face significant difficulty trying to manage your affairs. Depending on state law and your circumstances, court involvement may be necessary to appoint someone to act on your behalf.
Planning ahead gives you an opportunity to choose trusted decision-makers while you can still express your preferences.
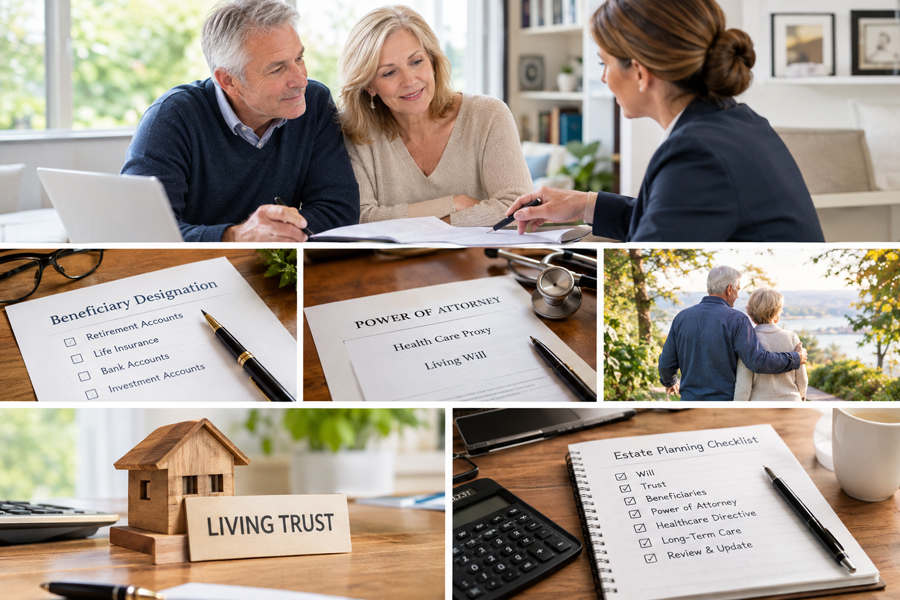
Essential Estate Planning Documents to Consider
Several documents can help protect your interests if you become incapacitated.
Durable power of attorney: This document authorizes someone you choose to handle specified financial or legal matters on your behalf. The authority granted and when it becomes effective depend on the document and applicable state law.
Healthcare proxy or healthcare power of attorney: This allows you to appoint someone to make healthcare decisions when you cannot make them yourself, as permitted by state law.
Living will or advance healthcare directive: This records your preferences concerning certain medical treatments and end-of-life care.
Will: A last will and testament explains how you want property distributed after your death and can address other matters, such as naming a guardian for minor children.
The precise names and requirements for these documents vary by state. An estate planning attorney can help you determine which documents are appropriate for your situation.
Protecting Your Financial Security Through Long-Term Care Planning
Another important consideration after age 50 is the potential cost of long-term care.
Depending on your health, preferences, and circumstances, you may eventually need assistance at home, adult day services, assisted living, or nursing home care. These services can create substantial expenses that affect your retirement savings and the assets you hope to pass on to your family.
Consider how you might pay for future care before a need arises.
Options worth exploring may include:
- Reviewing your retirement savings and anticipated healthcare expenses.
- Evaluating whether long-term care insurance is appropriate and affordable.
- Understanding which services may be covered by Medicare, Medicaid, or other programs, and the limitations of that coverage.
- Discussing potential Medicaid eligibility and asset-transfer rules with a qualified professional.
- Reviewing whether a trust or another legal arrangement fits your broader financial and estate planning goals.
Trusts and other planning tools do not automatically protect assets from long-term care costs or guarantee eligibility for government benefits. Their effects depend on how they are structured, when they are established, and the applicable rules.
Planning for incapacity and long-term care can help you preserve more control over your future while reducing uncertainty for your family.
3. Assuming a Will Automatically Avoids Probate
Creating a will is an important step in estate planning, but it generally does not eliminate probate.
Probate is the legal process used to administer certain assets after someone dies. Depending on state law and the circumstances of the estate, it may involve validating a will, identifying assets, paying debts and expenses, and distributing property to beneficiaries.
The process can take time and may involve legal and administrative costs. Some probate proceedings also become part of the public record.
Understanding how your assets will transfer is therefore just as important as writing down your wishes.
How a Living Trust May Help
A revocable living trust is one estate planning tool worth considering.
A properly established and funded living trust can allow assets held in the trust to pass to beneficiaries without going through probate. It can also provide instructions for managing those assets if you become incapacitated.
Depending on its terms, a trust may help you:
- Maintain greater privacy concerning the distribution of trust assets.
- Provide a structured inheritance for children or grandchildren.
- Specify when beneficiaries receive money or property.
- Arrange for continued management of assets if you become unable to manage them yourself.
- Simplify the transfer of certain assets after your death.
However, a trust does not automatically avoid probate for every asset. Property generally needs to be transferred into the trust or otherwise arranged to pass according to your plan. Assets left outside the trust may still require probate unless another transfer mechanism applies.
A revocable living trust also does not automatically reduce estate taxes or protect assets from creditors or long-term care expenses.
Whether a trust makes sense depends on your finances, family circumstances, state law, and planning objectives. An estate planning attorney can help you compare the benefits and costs of a trust with other available options.
4. Ignoring Estate Tax and Other Financial Consequences
Estate planning isn't just about deciding who inherits your property. It's also about understanding the potential financial consequences of transferring assets.
Depending on the size and structure of your estate, federal or state tax rules may affect how much your beneficiaries ultimately receive. In addition, retirement accounts, real estate, investments, and other assets may have different tax consequences when inherited or transferred.
However, it's important to distinguish between estate taxes and other taxes.
Federal estate tax applies only to estates that meet the applicable requirements. For deaths occurring in 2026, the federal estate tax basic exclusion amount is $15 million per individual, subject to applicable rules and adjustments. Some states have separate estate or inheritance taxes, with different thresholds and requirements.
Even if your estate is below the federal estate tax threshold, other tax considerations may still affect your beneficiaries.
Strategies Worth Discussing With a Professional
Depending on your circumstances, estate planning and financial planning strategies may include:
- Reviewing retirement account beneficiaries and distribution options.
- Considering the potential tax consequences of gifting assets during your lifetime.
- Evaluating charitable giving strategies that align with your goals.
- Coordinating investment, retirement, and estate plans.
- Reviewing how real estate and other appreciated assets may be treated when transferred or inherited.
- Considering whether a trust or other estate planning arrangement is appropriate.
Not every strategy benefits every family. For example, giving away property during your lifetime may affect your control over the asset, potential tax treatment, or eligibility for certain benefits.
A qualified tax professional, financial planner, and estate planning attorney can help you evaluate the options and avoid decisions that create unintended consequences.
The objective is not simply to minimize taxes. It's to make informed decisions that support your financial security and your wishes for your beneficiaries.
5. Failing to Review Your Estate Plan After Major Life Changes
An estate plan that once suited your circumstances may no longer reflect your wishes several years later.
Marriage, divorce, remarriage, the birth of grandchildren, a major inheritance, the sale of a business, or the purchase of real estate can all affect how your estate should be organized.
Blended families may require particular care. You might want to provide for your current spouse while also ensuring that children from a previous relationship receive an inheritance. Without careful planning, those goals may conflict.
Similarly, leaving assets outright to a beneficiary may not be appropriate if that person is a minor or has special circumstances that require additional planning.
Make Regular Estate Plan Reviews a Priority
Consider reviewing your estate plan every few years and whenever a significant life event occurs.
During your review, ask yourself:
- Does my will still reflect my wishes?
- Are my beneficiary designations current?
- Are the people I named to handle financial and healthcare decisions still appropriate choices?
- Have my assets, debts, or family relationships changed?
- Do my documents reflect the laws of my current state?
- Are my trust arrangements, if any, properly maintained and funded?
Keep copies of your documents in a secure but accessible location, and make sure the people who may need them know how to find them.
A regular review helps keep your estate plan aligned with your current circumstances rather than leaving your family to work with outdated instructions.
Your Estate Planning Checklist After Age 50
Getting started doesn't have to be overwhelming. Use this checklist to identify areas that may need attention.
- Review your will and determine whether it needs updating.
- Check beneficiary designations on retirement accounts and life insurance policies.
- Consider a durable power of attorney for financial matters.
- Establish appropriate healthcare decision-making documents and advance directives.
- Review how your home, investments, and other assets will transfer.
- Evaluate whether a living trust or another planning tool fits your needs.
- Consider how you would pay for potential long-term care.
- Discuss possible estate, inheritance, and income tax consequences with qualified professionals.
- Revisit your plan after major family, financial, or legal changes.
- Ensure that trusted individuals know where to locate essential documents.
You don't have to complete every step at once. Start by identifying the most significant gaps in your current plan, then work through them in a manageable order.
The Bottom Line: Protect Your Legacy by Planning Ahead
Smart estate planning after age 50 is about more than distributing money and property. It's about maintaining control over important decisions, preparing for unexpected circumstances, and helping your family understand your wishes.
By keeping beneficiary designations current, preparing for possible incapacity, evaluating long-term care needs, understanding probate, and reviewing potential tax consequences, you can reduce avoidable complications and create a more coordinated plan for the future.
Most importantly, remember that estate planning is an ongoing process, not a one-time task. The right plan for you will depend on your assets, family circumstances, goals, and state laws.
If you haven't reviewed your estate plan recently, consider making it a priority. A conversation with a qualified estate planning attorney and financial professional can help you identify the next steps toward protecting your assets and the legacy you want to leave behind.
Disclaimer: This article is for general educational purposes only and is not legal, tax, or financial advice. Estate planning laws and requirements vary by state. Consult appropriately qualified professionals about your individual circumstances.
All Images generated by AI
A special thank you to Sara W. at MindAlignPsychiatry for contributing this article.
Discover the secrets to aging gracefully and living your best life with Enjoying Aging – your ultimate resource for health, wellness, and financial wisdom!
If you enjoyed this article or have a topic you would like to suggest for a new article, please leave a comment in the form below.