0 How to Restart and Grow Your Business After Financial Setbacks: A Practical Guide
- Retirement Planning
- Author Sasha Moody
- 10-31-2026
How to Restart and Grow Your Business After Financial Setbacks: A Practical Guide
For many experienced entrepreneurs, the desire to build something meaningful doesn't disappear with age or retirement. In fact, stepping away from a business can sometimes rekindle the ambition to start again. But when a previous venture ended in financial difficulties, taking that next step may feel more intimidating than exciting.
Financial setbacks can leave lasting concerns about money, confidence, and the possibility of making the same mistakes twice. For entrepreneurs over 50, these concerns may be particularly significant. Retirement savings, family responsibilities, and long-term financial security can make starting another business seem like an unnecessary gamble.
However, a financial setback doesn't have to mark the end of your entrepreneurial journey. It can become an opportunity to reassess your goals, apply lessons from experience, and build a stronger business with a more sustainable approach.
The key isn't to recreate your previous business or rush into another venture. It's to develop a thoughtful business relaunch strategy that protects your financial well-being while creating opportunities for steady growth.
Whether you're reconsidering retirement, exploring a second career, or rebuilding after a business failure, the following strategies can help you move forward with greater confidence.
Understanding What Makes a Business Relaunch Successful
Restarting a business after financial setbacks requires more than enthusiasm and determination. It calls for an honest assessment of what happened previously, what you've learned, and what needs to change before you begin again.
A resilient business relaunch starts by treating past difficulties as valuable information rather than personal failure.
Ask yourself a few important questions:
- What financial or operational decisions contributed to the previous setback?
- Were there warning signs that went unnoticed?
- Did the business grow faster than its available cash flow?
- Were expenses, competition, or customer demand underestimated?
- What strategies worked well and deserve to be carried forward?
These questions aren't intended to dwell on past disappointments. Instead, they help identify the weaknesses that a new business plan should address.
According to the U.S. Bureau of Labor Statistics, approximately 22.1% of new business establishments in a historical cohort closed within their first year. While survival rates vary by industry and economic conditions, this illustrates why careful planning and financial discipline are so important.
Think of restarting a business like rebuilding a home after a severe storm. You wouldn't simply repair the visible damage and hope the next storm never arrives. You would strengthen the foundation, correct structural weaknesses, and prepare for future challenges.
The same principle applies to entrepreneurship.
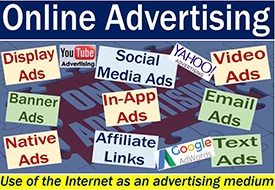
Content Marketing Offers the Highest Return On Investment
Online content marketing and advertising is currently the second-highest method of promoting businesses, following only Television, which, for now, remains in the number one position. Experts predict digital ads will surpass TV and never look back. For cost-effectiveness and the ability to target your audience, nothing matches the ROI of digital marketing. Learn More
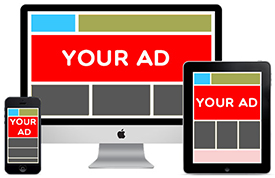
Digital Marketing Offers Three Opportunities To Reach Your Audience
Studies show that most people use their phones to search for content that addresses their current needs, then switch to their computers for more in-depth research before making a final decision or purchase. With three different platforms- computers, tablets, and phones- it is essential to ensure your audience can follow your content and ads on any device. The upside to this is that you have three opportunities to reach them. All of our Websites are developed to work flawlessly on all three platforms. Learn More
Your greatest advantage during a business comeback may be the experience you didn't have the first time around.
Most experienced entrepreneurs have looked back on earlier decisions and thought, "If I could do it all over again, I'd do things differently."
A business relaunch offers exactly that opportunity. You can preserve what worked, eliminate unnecessary expenses, improve your decision-making, and approach growth with a clearer understanding of the risks.
Start Small With a Business Model That Can Grow
One of the smartest ways to rebuild after a financial setback is to avoid committing substantial capital before you've demonstrated that customers are willing to pay for your products or services.
Rather than investing heavily in equipment, office space, employees, or inventory, consider a business model that allows you to test demand on a smaller scale.
This approach can be especially valuable for entrepreneurs who want to supplement retirement income, transition into self-employment, or rebuild financial stability without taking on excessive debt.
Consider an Online Reselling Business
Ecommerce reselling is one example of a business that can often be launched with relatively modest startup expenses.
Platforms such as eBay allow entrepreneurs to sell products without the overhead associated with maintaining a traditional retail location.
Depending on your interests and experience, you might begin by selling:
- Collectibles, antiques, or vintage merchandise
- Used books, household goods, or electronics
- Refurbished furniture or specialty equipment
- Clothing, accessories, or seasonal products
- Products sourced through estate sales, local auctions, or liquidation opportunities
You can begin with a limited selection of merchandise, evaluate customer demand, and gradually expand into categories that demonstrate consistent profitability.
Before getting started, however, it's important to understand the actual expenses involved. Reviewing eBay reselling business startup costs can provide a useful starting point for identifying potential costs and business formation considerations.
Remember that online reselling isn't automatically profitable. Platform fees, shipping expenses, packaging, returns, taxes, and unsold inventory can quickly reduce your margins.
Apply Your Existing Business Experience
For experienced entrepreneurs, an online business offers an opportunity to put established skills to work.
You may already understand how to negotiate prices, evaluate suppliers, manage inventory, identify customer needs, and deliver dependable service.
These abilities can give you a meaningful advantage over someone starting a business for the first time.
The goal is to combine that experience with a more disciplined financial approach.
Start by tracking every expense, including the purchase price of merchandise, shipping materials, selling fees, and other operating costs. Monitor how quickly products sell and which categories produce the strongest returns.
As sales increase, improve your listing process, inventory management, customer communication, and order fulfillment.
Most importantly, allow demonstrated customer demand and sustainable profits—not enthusiasm alone—to determine how quickly you expand.
Although ecommerce reselling is one possible starting point, the same principles apply to consulting, professional services, tutoring, freelance work, and other businesses that can begin with limited overhead.
A 7-Step Business Relaunch Toolkit for Long-Term Growth
Once you've identified a promising business opportunity, the next challenge is creating a practical strategy for moving forward.
A successful comeback doesn't require a complicated business plan or an overwhelming list of responsibilities. It requires a manageable set of actions that help you control risks, understand your customers, and make informed decisions.
The following seven steps can help establish that foundation.
1. Build a Reliable Business Support Network
Entrepreneurship can be rewarding, but making every decision alone can increase stress and lead to costly mistakes.
A strong support network provides access to practical advice, professional expertise, and encouragement when unexpected challenges arise.
Consider using a simple 3–2–1 support system:
- Three entrepreneurial peers: Connect with business owners who understand the challenges of starting, operating, and growing a company.
- Two professional advisers: Depending on your business, these might include an accountant, attorney, insurance specialist, or experienced operations consultant.
- One accountability partner: Choose someone who can help you stay focused on your goals and review your progress regularly.
If you're restarting an online reselling business, connecting with someone experienced in ecommerce can be especially helpful. They may offer valuable insights into platform fees, inventory management, shipping, and customer returns.
You don't need a large professional network. A small group of knowledgeable, dependable people can make a substantial difference.
2. Research Your Market Before Investing Heavily
One of the most common mistakes entrepreneurs make is assuming that a promising idea automatically translates into customer demand.
Before committing significant money, take time to understand the competitive landscape.
Start by identifying five to seven businesses offering similar products or services.
For each competitor, examine:
- Their primary customers
- Product or service pricing
- Best-selling products or most visible offers
- Customer reviews and recurring complaints
- Areas where their products or services may fall short
You don't need weeks of research to uncover useful information.
Try dividing the process into two focused sessions.
During the first session, gather information about your competitors and their customers.
During the second, identify a specific opportunity to distinguish your business.
For example, if competitors offer similar products but receive frequent complaints about slow shipping or poor communication, dependable service could become a valuable selling point.
The purpose of competitive research isn't to copy successful businesses. It's to discover how you can serve customers more effectively.
3. Develop a Clear Marketing Message Before Spending on Advertising
Marketing is essential to business growth, but advertising dollars can disappear quickly when a business hasn't clearly defined its customers or its value.
Before purchasing ads, establish a simple, convincing explanation of why customers should choose your business.
Begin by answering three questions:
- Who is your ideal customer?
- What problem are they trying to solve?
- Why is your product or service a better choice for their needs?
Use these answers to develop a message that focuses on customer benefits rather than simply describing what you sell.
For example, instead of advertising 'quality refurbished furniture,' a business might emphasize 'affordable, carefully restored furniture that gives your home character without the cost of buying new.'
The second message communicates a more specific benefit.
You can also learn from customer questions, product reviews, and conversations with potential buyers.
These insights often reveal what matters most to your audience.
Once your message is clear, test it through low-cost channels such as social media, email, referrals, or relevant community groups before increasing your advertising budget.
4. Create a Simple, One-Page Marketing Plan
A business relaunch doesn't require an elaborate marketing strategy with dozens of campaigns.
For a small business rebuilding its financial foundation, a focused plan is often more useful.
Your initial marketing plan should identify:
- Your primary audience: The customers most likely to purchase your products or services.
- Your core offer: What you're selling and the value it provides.
- Your main marketing channel: Where you'll concentrate most of your efforts.
- A secondary channel: An alternative method for reaching customers.
- Your monthly marketing budget: An amount you can reasonably afford.
- Your weekly marketing activities: Specific actions you can repeat consistently.
For example, a consulting business might focus primarily on referrals from professional contacts, use email as a secondary marketing channel, and commit to contacting ten potential clients each week.
An e-Commerce reseller might focus on improving marketplace listings while using a social media account to attract interested buyers.
Keep your marketing expenses separate from essential operating costs.
Avoid spending money on advertising that should be reserved for inventory replenishment, insurance, bookkeeping, or other necessary obligations.
Review your results regularly and concentrate on the activities producing measurable customer interest and sales.
5. Rebuild Business Relationships Through Consistent Networking
Experienced entrepreneurs often possess something that new business owners haven't yet developed: years of professional relationships.
Former colleagues, customers, suppliers, and industry contacts may become valuable sources of advice, referrals, or business opportunities.
Reconnecting with these individuals can be an effective and affordable way to rebuild momentum.
Start with a manageable networking goal.
For the next 30 days, consider scheduling two new business conversations each week.
During these discussions, focus on learning about the other person's needs rather than immediately promoting your business.
Ask practical questions such as:
'Are you seeing any changes in what customers are looking for?'
'Do you know anyone who might benefit from this type of service?'
"Who would you recommend I speak with about this market?"
Follow up with new contacts within a few days and keep a simple record of conversations, referrals, and potential opportunities.
Networking works best when it becomes a consistent relationship-building activity rather than an occasional attempt to generate immediate sales.
6. Evaluate Financial and Operational Risks Before They Become Problems
Every business faces uncertainty. The objective isn't to eliminate all risk, which is impossible, but to identify the most significant threats and prepare reasonable responses.
Start by listing ten potential risks that could affect your new business.
These might include:
- Lower-than-expected sales
- Unexpected operating expenses
- Slow-paying customers
- Supplier disruptions
- Excess inventory
- Rising shipping or transportation costs
- Changes in marketplace fees or policies
- Equipment failures
- Liability or insurance concerns
- Personal circumstances that temporarily limit your availability
Next, rate each risk according to its likelihood and potential financial impact.
For higher-priority risks, identify at least one preventive action.
For example, if unpredictable sales are a concern, maintain an operating cash reserve and avoid purchasing excessive inventory.
If supplier reliability is an issue, research alternative sources before problems arise.
If you depend heavily on one sales platform, consider ways to diversify your customer relationships over time.
Review your risk assessment at least annually and whenever your business experiences significant changes.
A practical risk management plan can help prevent temporary difficulties from developing into another major financial setback.
7. Establish Clear Financial Goals Before Expanding
Business growth can be exciting, especially when early sales begin to restore confidence.
However, expanding too quickly can recreate the same financial pressures that contributed to a previous setback.
Before increasing expenses, establish measurable conditions that must be met.
For example:
- Increase inventory only after demonstrating consistent profitability over a defined period.
- Add a new product category after confirming sufficient customer demand.
- Hire assistance when recurring revenue can reasonably support the additional expense.
- Invest in new equipment when expected benefits justify the cost.
- Reevaluate your business structure when liability, contracts, or operational complexity increase.
These decisions should be based on accurate financial records rather than sales revenue alone.
A business generating substantial sales may still struggle if operating costs consume most of its income.
Monitor profit margins, cash flow, available reserves, and outstanding obligations.
It's also important to establish personal financial boundaries.
If you're approaching retirement or already retired, consider how business losses could affect your household expenses, savings, and future income needs.
A financial professional can help you determine how much capital you can reasonably put at risk without undermining essential long-term goals.
Sustainable business growth should strengthen your financial position, not jeopardize the security you've worked years to establish.
Business Relaunch FAQs: Managing Risk, Cash Flow, and Legal Responsibilities
Q. How Can I Reduce Financial Risk When Restarting a Business Later in Life?
The best approach is to begin with small, affordable investments and expand gradually as your business demonstrates consistent results.
Establish a startup budget, separate business and personal finances, and avoid risking money needed for essential living expenses or retirement security.
Rather than investing heavily before making your first sale, test customer demand and use the results to guide future decisions.
Q. What Should I Do if My New Business Experiences Cash Flow Problems?
Start by reviewing when money enters and leaves the business.
Track expected sales receipts, upcoming bills, inventory expenses, and other financial obligations.
Depending on your business model, you may be able to improve cash flow by collecting deposits, shortening payment terms, reducing unnecessary purchases, or offering prepaid services.
For an online reselling business, focus on selling existing inventory before committing additional money to new merchandise.
A simple weekly cash flow forecast can help identify potential shortages before they become emergencies.
Q. When Should I Consider Forming an LLC?
A limited liability company (LLC) is a business structure established under state law that generally provides a degree of separation between the business's obligations and its owners' personal assets.
Forming an LLC may be worth considering when your business involves significant liability exposure, formal contracts, employees, or expanding operations.
However, an LLC doesn't eliminate every form of personal liability, and forming one doesn't automatically provide tax savings.
The appropriate timing depends on your business activities, state requirements, and financial circumstances.
Consult an attorney or qualified tax professional before making a decision.
Q. Can I Restart a Business Without Using My Retirement Savings?
In many cases, yes.
Consider business models with limited startup expenses, such as consulting, freelancing, online services, or small-scale ecommerce.
Begin with equipment and resources you already own whenever possible.
Avoid large inventory purchases, expensive branding projects, unnecessary subscriptions, or long-term financial commitments until the business demonstrates sufficient demand.
You may also choose to reinvest a portion of business profits into future growth.
The objective is to create a business that can gradually support its own expansion rather than relying heavily on personal savings.
Q. Should I Register My Business Before Making Consistent Sales?
Business registration requirements depend on your location, legal structure, and type of business.
Some entrepreneurs begin by testing a business idea as sole proprietors, while others establish a formal legal entity before accepting customers or entering contracts.
Even a small business may need licenses, permits, tax registrations, or other approvals before operating.
If you're considering an LLC, review your state's filing requirements and seek professional guidance about liability protection, taxes, and ongoing compliance.
Don't assume that waiting until your business generates steady revenue eliminates legal obligations.
Q. How Long Does It Take to Rebuild a Profitable Business?
There is no universal timeline.
Profitability depends on factors such as your industry, startup expenses, customer demand, pricing, competition, and operating efficiency.
Some service-based businesses can begin earning revenue relatively quickly, while inventory-heavy or equipment-intensive businesses may require more time and capital.
Instead of focusing exclusively on how quickly you can grow, establish short-term milestones that measure progress.
These might include securing your first paying customers, covering monthly operating expenses, maintaining positive cash flow, or reaching a consistent profit target.
Progress measured through realistic financial milestones is more useful than comparing your comeback with someone else's success story.
Build Your Business Comeback One Step at a Time
Restarting a business after financial setbacks takes courage, patience, and a willingness to approach familiar challenges differently.
For experienced entrepreneurs, especially those reconsidering retirement or exploring a new chapter after 50, the opportunity isn't simply to start another business. It's to create something better suited to your current priorities, financial circumstances, and personal goals.
The lessons learned from previous ventures can become powerful tools for making smarter decisions.
You may now recognize warning signs earlier, understand the importance of maintaining cash reserves, or appreciate the value of reliable professional advice.
Perhaps you've also discovered that building a successful business doesn't always mean creating the largest company possible.
Sometimes, success means operating a smaller, more manageable business that generates dependable income, provides personal satisfaction, and allows you to maintain the lifestyle you value.
Begin by identifying one realistic opportunity. Research your market, establish financial safeguards, and create a plan that allows you to test your ideas without taking unnecessary risks.
Then commit to making steady progress each week.
Your previous financial setbacks may be part of your business history, but they don't have to determine your entrepreneurial future.
With careful planning, realistic expectations, and the wisdom gained through experience, your next business venture can become a rewarding new chapter—one built on stronger foundations and a clearer vision of success.
Disclaimer: This article is for general educational purposes only and is not legal, tax, or financial advice. Business laws and requirements vary by state. Consult appropriately qualified professionals about your individual circumstances.
All Images generated by AI
A special thank you to Sasha Moody at The Patient Investor for contributing this article.
Sasha Moody is ‘The Patient Investor.’ She created her website to help people grow their wealth steadily over time. As someone who recently began learning about the importance of investing, Sasha wanted to help others new to investing build their confidence so they, too, can take advantage of its wealth-building potential. She knows how daunting it can be to learn everything there is to know about investing, so she compiled resources she found helpful when she was getting started and placed them on The Patient Investor Website.
Discover the secrets to aging gracefully and living your best life with Enjoying Aging – your ultimate resource for health, wellness, and financial wisdom!
If you enjoyed this article or have a topic you would like to suggest for a new article, please leave a comment in the form below.